High-Yield Savings Accounts 2026: 4% APY & Beyond
Advertisements
The financial landscape of 2026 presents new opportunities for savers, with High-Yield Savings Accounts 2026 offering competitive rates. This analysis delves into options exceeding 4% APY, providing a comprehensive comparison for informed decisions. Understanding market trends and institutional offerings is crucial for maximizing returns.
Exploring High-Yield Savings Accounts in 2026: Finding Rates Above 4% APY (COMPARISON/ANALYSIS) is shaping today’s agenda with new details released by financial institutions and market analysts. This update prioritizes what changed, why it matters, and what to watch next in the high-yield savings landscape. Savers are keenly observing the market for optimal opportunities.
Understanding the Current Landscape of High-Yield Savings Accounts
The year 2026 is poised to be a significant period for savers, as economic conditions and Federal Reserve policies continue to influence interest rates. High-yield savings accounts have emerged as a primary vehicle for individuals looking to grow their cash reserves beyond traditional checking or low-interest savings options. The pursuit of rates above 4% APY has become a realistic goal for many.
As the market evolves, understanding the nuances of these accounts is crucial for making informed financial decisions. This section will lay the groundwork for what defines a high-yield account and the factors driving their current attractiveness. It is imperative to distinguish between marketing claims and actual, sustainable returns.
Financial experts emphasize that while high APY is a major draw, other factors such as fees, accessibility, and insurance coverage also play a vital role. A holistic approach ensures that savers not only earn more but also maintain peace of mind regarding their funds. The current environment favors those who are diligent in their research.
Factors Driving High APY in 2026
Several key macroeconomic factors are contributing to the ability of financial institutions to offer attractive APY rates. Federal Reserve policies, including adjustments to the federal funds rate, directly impact what banks can offer. A higher federal funds rate generally translates to higher savings rates across the board.
Competition among online banks and fintech companies also plays a significant role in pushing rates upward. These institutions often have lower overhead costs compared to traditional brick-and-mortar banks, allowing them to pass on more savings to their customers. This competitive environment benefits consumers seeking higher returns on their deposits.
Market demand for deposits is another critical element. Banks that need to attract more deposits to fund their lending activities or meet regulatory requirements are often willing to offer more competitive rates. This dynamic creates a favorable environment for individuals exploring High-Yield Savings Accounts in 2026.
- Federal Reserve interest rate decisions
- Increased competition among online banks
- Banks’ demand for stable deposit funding
Key Features to Look for in High-Yield Savings Accounts
When evaluating high-yield savings accounts, the Annual Percentage Yield (APY) is undoubtedly the most prominent feature. However, a comprehensive analysis requires looking beyond just the headline rate to understand the full value proposition. Hidden fees or restrictive terms can significantly diminish the effective return on your savings.
Accessibility to your funds is another critical consideration. While savings accounts are not designed for frequent transactions, understanding withdrawal limits and transfer times is important for managing your liquidity needs. Some accounts might offer higher rates but come with more stringent access rules.
Finally, ensuring your funds are protected is paramount. Always verify that the financial institution offering the high-yield account is FDIC-insured (for banks) or NCUA-insured (for credit unions). This insurance protects your deposits up to $250,000 per depositor, per institution, in case of bank failure, providing a crucial safety net for your savings.
Understanding APY vs. Interest Rate
Many savers confuse Annual Percentage Yield (APY) with a simple interest rate, but there’s a crucial distinction. The interest rate is the percentage at which interest is calculated, while APY reflects the actual annual return on an investment, taking into account the effect of compounding interest. This means APY provides a more accurate picture of your earnings over a year.
When comparing different High-Yield Savings Accounts in 2026, always prioritize APY as the primary metric for earnings potential. An account with a slightly lower stated interest rate but more frequent compounding (e.g., daily) could potentially yield a higher APY than one with a higher stated rate but less frequent compounding (e.g., monthly). This difference can add up over time.
It is important to note that APY can fluctuate. While a bank might advertise a high APY, it’s essential to understand if the rate is fixed or variable. Most high-yield savings accounts offer variable rates, meaning they can change based on market conditions. Monitoring these changes is part of prudent financial management.
Top Contenders for High-Yield Savings Accounts in 2026 (4% APY and Above)
As we delve into 2026, several financial institutions are consistently standing out for their competitive high-yield savings offerings. These banks, primarily online-only or those with strong digital platforms, leverage their lower operational costs to provide superior rates to consumers. Their focus on digital banking streamlines processes and reduces overhead.
While specific rates are subject to market fluctuations, institutions like Synchrony Bank, Ally Bank, Marcus by Goldman Sachs, and Discover Bank have historically been strong performers in this space. They often lead the market in offering rates that are well above the national average, making them attractive options for savers. Their commitment to customer service also sets them apart.
Prospective savers should regularly check the websites of these and other reputable online banks for the most up-to-date APY offerings. The competitive nature of this market means rates can change frequently, so staying informed is key to securing the best possible returns on High-Yield Savings Accounts in 2026. Diligence in tracking rates pays off.
Comparative Analysis of Leading Providers
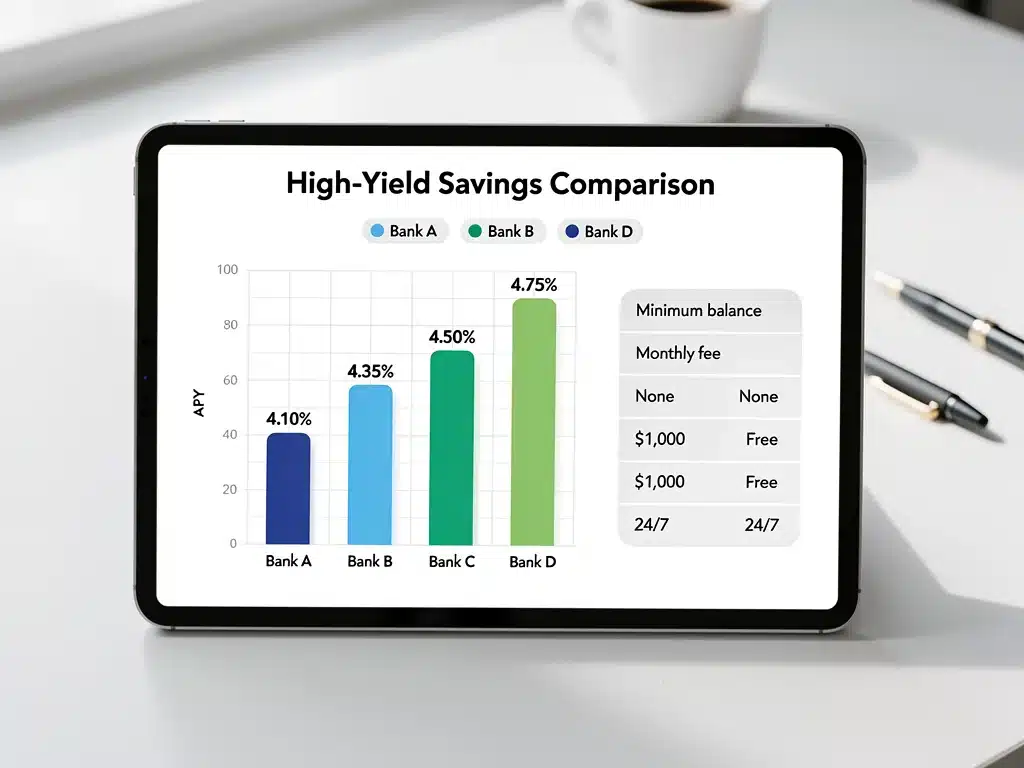
When comparing leading providers for High-Yield Savings Accounts in 2026, it’s not just about the highest APY, but also the overall customer experience and additional benefits. Ally Bank, for instance, is often praised for its user-friendly online interface, 24/7 customer service, and lack of monthly maintenance fees, making it a strong all-around choice for many savers.
Marcus by Goldman Sachs often offers highly competitive rates and boasts a seamless digital experience, appealing to those who prefer a streamlined banking approach. They typically have no minimum balance requirements or monthly fees, which adds to their appeal. Their reputation as a major financial institution also provides a sense of security.
Discover Bank, another strong contender, combines competitive APY with excellent customer service and a robust mobile app. They also offer cash back on debit card purchases, a unique perk for a savings account. Synchrony Bank frequently features among the top rates and provides easy online access to funds, making it a solid option for those prioritizing high returns.
Strategies for Maximizing Your High-Yield Savings
To truly maximize the benefits of High-Yield Savings Accounts in 2026, a proactive approach to financial management is essential. Simply opening an account is the first step; continuous engagement with your savings strategy can yield significantly better results. This involves regular contributions and monitoring market conditions to ensure your money is working as hard as possible.
Automating your savings contributions is one of the most effective strategies. By setting up recurring transfers from your checking account to your high-yield savings account, you ensure consistent growth without needing to remember to move funds manually. This disciplined approach eliminates procrastination and builds wealth steadily over time.
Furthermore, regularly reviewing the APY offered by your current institution and comparing it with competitors can help you identify opportunities to switch to a better-performing account. While switching banks might seem like a hassle, the potential increase in earnings can be substantial, especially on larger savings balances. Staying informed about the best High-Yield Savings Accounts in 2026 is critical.
Leveraging Tiered Accounts and Bonuses
Some high-yield savings accounts offer tiered interest rates, where higher balances qualify for higher APYs. If you have substantial savings, exploring these tiered options can significantly boost your earnings. It’s important to understand the balance thresholds and how they apply to your specific savings goals when considering these accounts.
Additionally, many banks offer sign-up bonuses or promotional rates for new customers. While these can be attractive, always read the fine print to understand the requirements for earning the bonus and how long the promotional rate lasts. Sometimes, the long-term APY after the promotional period might not be as competitive, so a thorough evaluation is necessary when looking at High-Yield Savings Accounts in 2026.
Combining these strategies, such as automating savings into a tiered account and taking advantage of beneficial sign-up bonuses, can create a powerful growth trajectory for your funds. These tactics are designed to enhance your overall savings strategy and ensure you are getting the most out of your High-Yield Savings Accounts in 2026.
Potential Risks and Considerations for Savers
While High-Yield Savings Accounts in 2026 offer attractive returns, it’s crucial for savers to be aware of potential risks and important considerations. No financial product is entirely without its caveats, and understanding these can help in making a more robust and secure financial plan. Being informed about these aspects ensures a well-rounded decision.
One primary consideration is the variable nature of interest rates. Most high-yield accounts offer variable APYs, meaning the rate can change at any time based on market conditions, particularly Federal Reserve policy. While rates might be high now, they could decrease in the future, impacting your projected earnings. This variability requires ongoing monitoring.
Another factor to watch out for is introductory or promotional rates. Some banks might offer an exceptionally high APY for a limited period to attract new customers. After this period, the rate may revert to a much lower, standard APY. Always verify the long-term rate when considering High-Yield Savings Accounts in 2026 to avoid disappointment.
Navigating Fees and Minimum Balance Requirements
While many online high-yield savings accounts boast no monthly maintenance fees, it’s essential to scrutinize the fee schedule for other potential charges. These can include fees for excessive withdrawals, wire transfers, or insufficient funds. Even small fees can erode your earnings over time, especially on smaller balances. A comprehensive review of all potential costs is advised.
Some accounts may also impose minimum balance requirements to earn the advertised high APY. If your balance falls below this threshold, you might earn a significantly lower rate or even incur fees. Understanding these requirements upfront is crucial to ensure your account continues to perform as expected. This is particularly relevant when researching High-Yield Savings Accounts in 2026.
It’s also worth noting that some accounts might require a minimum initial deposit to open. While this is typically a one-time requirement, it can be a barrier for some savers. Always compare these terms across different providers to find an account that aligns with your financial capacity and goals, ensuring no unexpected surprises.
The Role of Online Banks in High-Yield Offerings
Online banks have fundamentally transformed the landscape of savings accounts, particularly in the high-yield sector. Their business model, which typically involves lower operational costs due to the absence of physical branches, allows them to offer significantly more attractive Annual Percentage Yields (APYs) compared to traditional brick-and-mortar institutions. This efficiency directly benefits the consumer.
This shift has democratized access to higher returns on savings, making it easier for individuals across the United States to find competitive rates. The convenience of managing accounts entirely online, from opening to transactions, further enhances their appeal. This digital-first approach aligns with modern consumer preferences for accessibility and speed.
As we continue Exploring High-Yield Savings Accounts in 2026: Finding Rates Above 4% APY (COMPARISON/ANALYSIS), it becomes clear that online banks will remain at the forefront of innovation and competitive offerings. Their agility in adapting to market changes and their commitment to digital solutions make them indispensable players in the high-yield savings market. They are continuously pushing the boundaries of what’s possible for savers.
Advantages of Online-Only Platforms
One of the primary advantages of online-only platforms is their ability to offer higher APYs. Without the overhead of maintaining a vast network of physical branches and associated staff, these banks can allocate more of their resources to providing better interest rates to their depositors. This direct cost-saving translates into more money in savers’ pockets.
Another significant benefit is the enhanced convenience and accessibility. Online banks typically offer robust mobile apps and intuitive web platforms that allow customers to manage their accounts 24/7 from anywhere. This includes checking balances, transferring funds, and even depositing checks remotely, which is a major draw for busy individuals seeking High-Yield Savings Accounts in 2026.
Furthermore, online banks are often pioneers in adopting new financial technologies, leading to more secure and efficient banking experiences. Features like advanced encryption, multi-factor authentication, and seamless integration with other financial tools are common. This technological edge provides both security and a smoother user experience for those with High-Yield Savings Accounts in 2026.
Forecasting Interest Rates and Economic Outlook for 2026
Forecasting interest rates for 2026 involves analyzing a complex interplay of economic indicators, central bank policies, and global financial trends. While predicting exact rates is challenging, current projections suggest a continued focus on inflation management by the Federal Reserve, which will be a key determinant of savings rates. This economic environment is critical for High-Yield Savings Accounts in 2026.
Experts are closely watching inflation data, employment figures, and global geopolitical events, all of which can influence the Federal Reserve’s decisions on the federal funds rate. Any sustained period of high inflation could prompt the Fed to maintain higher rates, which would generally benefit savers with high-yield accounts. Conversely, a significant economic slowdown could lead to rate cuts.
Savers should remain agile and informed, understanding that the financial landscape is dynamic. While the current outlook for High-Yield Savings Accounts in 2026 is promising for rates above 4% APY, staying updated on economic news and Federal Reserve announcements will be essential for adjusting personal savings strategies as needed. Flexibility is key in this evolving market.
Impact of Federal Reserve Policy on APY
The Federal Reserve’s monetary policy, particularly its decisions regarding the federal funds rate, directly impacts the APY offered by High-Yield Savings Accounts. When the Fed raises its target rate, banks typically follow suit by increasing the interest rates they offer on deposits to attract funds. This direct correlation is a fundamental aspect of the financial system.
Conversely, if the Federal Reserve decides to lower rates, banks will likely reduce the APY on savings accounts. This is why understanding the Fed’s stance on inflation and economic growth is paramount for anyone considering High-Yield Savings Accounts in 2026. The central bank’s actions reverberate throughout the entire banking sector and directly affect personal finance.
Therefore, staying abreast of Federal Reserve meetings and statements is not just for economists; it’s a practical necessity for savers. These announcements provide valuable insights into the future direction of interest rates and can help individuals anticipate changes in the returns on their High-Yield Savings Accounts. Proactive monitoring helps maintain optimal savings performance.
Comparing High-Yield Savings with Other Investment Options
While High-Yield Savings Accounts in 2026 offer attractive returns and low risk, it’s important to understand how they compare to other investment vehicles. For short-term goals and emergency funds, high-yield savings are often superior due to their liquidity and principal protection. However, for long-term growth, other options might be more suitable, depending on individual risk tolerance.
Certificates of Deposit (CDs) often offer slightly higher fixed interest rates than high-yield savings accounts, especially for longer terms. However, CDs typically lock up your money for a specified period, imposing penalties for early withdrawal. The trade-off is a guaranteed rate for the duration of the term, which can be appealing in a volatile rate environment.
For those willing to take on more risk for potentially higher returns, investments in the stock market, mutual funds, or bonds could be considered. These options carry greater market volatility and risk of principal loss but historically offer higher long-term growth. The choice depends on your financial goals, time horizon, and personal comfort with risk.
When to Choose High-Yield Savings Over Other Investments
High-Yield Savings Accounts are ideal for funds you need to access relatively quickly, such as an emergency fund, down payment savings for a house, or money set aside for a large purchase within the next few years. Their liquidity and FDIC insurance provide a level of security unmatched by riskier investments. This makes them a cornerstone of any sound financial plan.
They are also an excellent choice for individuals who are risk-averse and prioritize capital preservation over aggressive growth. Earning 4% APY or more on your savings with virtually no risk of losing your principal is a compelling proposition, especially in an unpredictable economic climate. This stability is a significant advantage of High-Yield Savings Accounts in 2026.
Furthermore, for those just starting their savings journey, a high-yield savings account provides a clear, understandable way to grow money without the complexities of the stock market. It’s a foundational tool for building financial discipline and seeing tangible returns on your efforts, making it a smart starting point for many individuals.
Regulatory Environment and Consumer Protection
The regulatory environment plays a crucial role in ensuring the safety and reliability of High-Yield Savings Accounts in 2026. Agencies like the Federal Deposit Insurance Corporation (FDIC) and the National Credit Union Administration (NCUA) provide essential consumer protection by insuring deposits up to $250,000 per depositor, per institution. This insurance is a cornerstone of trust in the banking system.
Beyond deposit insurance, various consumer protection laws and regulations govern how financial institutions operate, including transparency in fees, interest rate disclosures, and fair banking practices. These regulations are designed to protect consumers from predatory practices and ensure they have clear information when making financial decisions. Adherence to these rules is mandatory for all reputable institutions.
Staying informed about these protections and verifying that your chosen financial institution complies with all relevant regulations is a fundamental step for any saver. This due diligence ensures that your funds are not only earning a competitive APY but are also secure and accessible under established legal frameworks. Consumer protection is a non-negotiable aspect of High-Yield Savings Accounts in 2026.
FDIC and NCUA Insurance Explained
FDIC insurance protects deposits held in banks, while NCUA insurance protects deposits in credit unions. Both agencies provide coverage up to $250,000 per depositor, per insured institution, for each account ownership category. This means if you have multiple accounts at the same institution under different ownership categories (e.g., individual, joint, retirement), each might be separately insured.
This insurance is vital because it guarantees that even if an insured bank or credit union fails, you will get your money back up to the coverage limit. This eliminates the risk of losing your principal due to institutional insolvency, making High-Yield Savings Accounts an incredibly safe place for your cash. It’s a fundamental safeguard against financial shocks.
When selecting a high-yield savings account, always confirm that the institution is FDIC or NCUA insured. This information is typically prominently displayed on their website. Do not rely solely on high APY claims; verify the insurance status to ensure your savings are protected. This simple check provides immense peace of mind when considering High-Yield Savings Accounts in 2026.
| Key Feature | Benefit for Savers |
|---|---|
| High APY (4%+) | Significant growth on savings, outpacing inflation. |
| FDIC/NCUA Insured | Principal protected up to $250,000, ensuring safety. |
| Low/No Fees | Maximizes net earnings, avoids erosion of savings. |
| Easy Online Access | Convenient 24/7 management and fund transfers. |
Frequently Asked Questions About High-Yield Savings Accounts in 2026
A High-Yield Savings Account offers significantly higher interest rates (APY) than traditional savings accounts, often due to lower overhead costs of online banks. Regular savings accounts typically have very low APYs, barely keeping pace with inflation, while high-yield options aim to grow your money more effectively.
Yes, reputable High-Yield Savings Accounts offered by banks are FDIC-insured up to $250,000 per depositor, per institution. This insurance protects your principal in the event of a bank failure. Always verify the FDIC or NCUA insurance status of any institution before depositing funds.
The APY on High-Yield Savings Accounts is primarily influenced by the Federal Reserve’s federal funds rate, overall economic conditions, and competition among financial institutions. Online banks, with lower operating costs, often lead in offering higher rates to attract deposits and compete in the market.
Generally, yes. While they are savings accounts, most high-yield options offer easy online access to funds through electronic transfers. However, they may have limits on the number of monthly withdrawals or specific transfer times. Always check the account’s terms for withdrawal policies.
When comparing High-Yield Savings Accounts in 2026, prioritize the APY, ensure FDIC/NCUA insurance, check for any monthly fees or minimum balance requirements, and assess the ease of access to your funds. Reading customer reviews can also provide insight into service quality.
Looking Ahead: Strategic Savings in a Dynamic Market
The landscape for High-Yield Savings Accounts in 2026 remains dynamic, presenting both opportunities and challenges for savers. As economic conditions and central bank policies continue to evolve, staying informed and adaptable will be crucial for maximizing returns. The pursuit of rates above 4% APY is a realistic goal, provided individuals engage in diligent research and comparison.
The shift towards online banking platforms will likely continue to drive competition and innovation, benefiting consumers seeking higher yields without excessive fees. Savers should prioritize institutions that offer a combination of competitive APY, strong consumer protections like FDIC insurance, and user-friendly access to funds. This holistic approach ensures both growth and security for your savings.
Ultimately, the success of your savings strategy in 2026 will hinge on proactive management: automating contributions, regularly reviewing rates, and understanding the fine print of each account. By adopting these practices, individuals can effectively navigate the market and make their money work harder for their financial goals, leveraging the best High-Yield Savings Accounts in 2026.


