FAFSA Changes 2026-2027: Parent Guide to Recent Updates
Advertisements
FAFSA Changes for 2026–27 include updated asset exclusions, revised Pell Grant rules, continued use of the Student Aid Index, direct IRS tax-data transfer, and specific contributor requirements. Families should review current federal rules together with state and college financial-aid deadlines.
FAFSA Changes remain important for families planning college costs during the 2026–27 award year. The current FAFSA cycle is already underway, so applicants should focus on completing or correcting forms rather than waiting for future changes to take effect.
The 2026–27 FAFSA became available beginning October 1, 2025. The federal submission deadline is June 30, 2027, but individual states and colleges can establish much earlier priority deadlines for grants, scholarships, and institutional aid.
Several elements introduced through FAFSA simplification remain in place, while additional statutory changes specifically affect the 2026–27 cycle. Understanding which rules are genuinely new can help families avoid relying on guidance written for earlier award years.
Decoding the FAFSA Simplification Act
The FAFSA Changes Simplification Act changed the federal student-aid application and need-analysis system over several award years. Major reforms included replacing the Expected Family Contribution with the Student Aid Index and restructuring how Federal Pell Grant eligibility is calculated.
For 2026–27, families should distinguish those continuing reforms from newer statutory adjustments. The Student Aid Index remains central to federal need analysis, but Congress changed several asset and Pell Grant provisions that apply specifically to this award year.
Understanding the current FAFSA Changes is therefore more useful than treating every simplification provision as newly introduced for 2026–27. Some rules have already operated for multiple FAFSA cycles, while others became effective with the current form.
Key Changes to the FAFSA Changes Form and Process
The 2026–27 FAFSA continues the streamlined structure introduced through FAFSA simplification. Applicants and required contributors complete different sections according to family circumstances, and online filers generally use their individual StudentAid.gov accounts to access and sign the form.
Federal tax information is transferred directly from the IRS after the student and required contributors provide consent and approval. This process reduces some manual tax-data entry, although applicants may still need tax records and other financial documents to answer additional questions.
The application is already available for the 2026–27 award year, so families should verify school and state deadlines now. Some aid programs have limited funding or priority dates considerably earlier than the final federal deadline of June 30, 2027.
Introduction of the Student Aid Index (SAI)
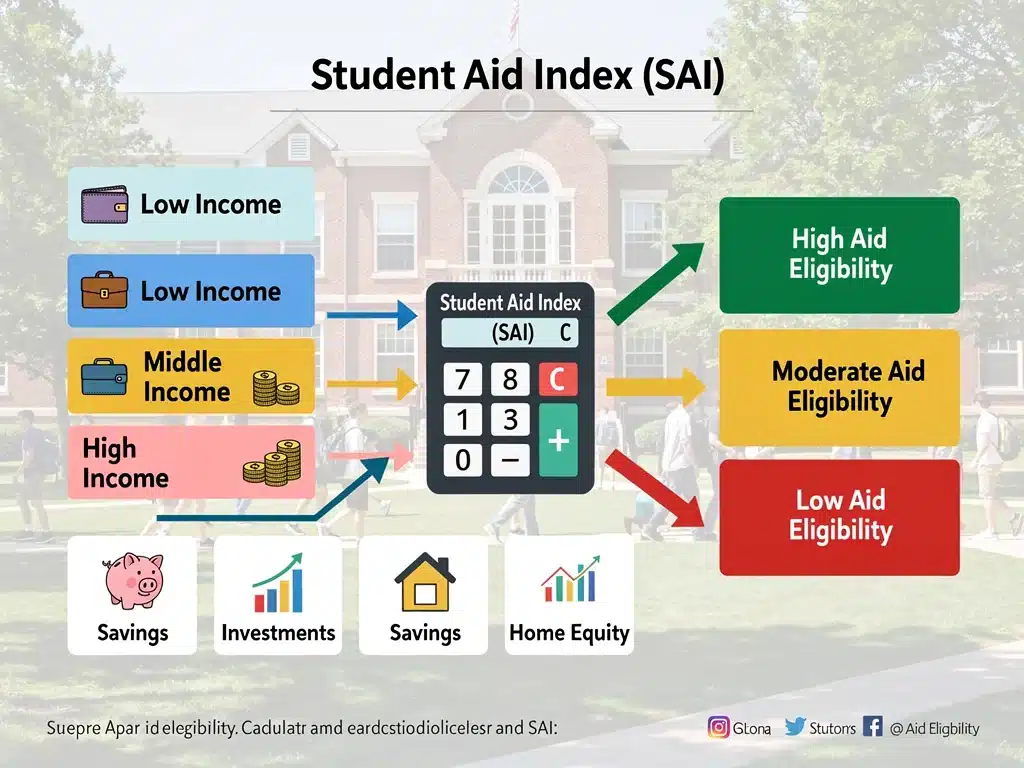
The Expected Family Contribution, or EFC, was replaced by the Student Aid Index beginning in earlier FAFSA Changes cycles. The SAI is an eligibility index used in federal need analysis and should not be interpreted as the exact amount a family must pay for college.
One important difference is that the number of family members attending college is not used directly in the federal SAI calculation. The FAFSA still asks about the number in college, and schools may consider that information when evaluating documented special circumstances.
The SAI can also be negative, reflecting particularly high calculated financial need. Families should remember that the index is only one component of financial-aid packaging, which also depends on cost of attendance, Pell eligibility, other aid, and institutional policies.
- The SAI replaced the Expected Family Contribution.
- The number in college does not directly reduce the federal SAI.
- A negative SAI can indicate a comparatively high level of calculated financial need.
Impact on Federal Pell Grant Eligibility
Federal Pell Grant eligibility continues to use formulas involving family size, adjusted gross income, poverty guidelines, and the Student Aid Index. The maximum scheduled Pell Grant award for the 2026–27 award year is $7,395.
For 2026–27, an additional rule can make a student ineligible for a Pell Grant when the SAI equals or exceeds twice the maximum Pell Grant amount. With a $7,395 maximum, that threshold is $14,790, subject to specified exceptions.
Families should therefore avoid assuming that broader FAFSA Changes simplification automatically means every applicant will receive more Pell Grant aid. Eligibility and award amounts depend on the student’s actual financial information and the federal formulas applicable to the award year.
Expanded Eligibility and Pell Grant Rules
Maximum and minimum Pell Grant eligibility can be determined using adjusted gross income, family size, state of residence, and federal poverty guidelines. The precise income threshold varies because the formula accounts for family circumstances rather than using one national income cutoff.
The Student Aid Index can also affect Pell Grant eligibility when a student does not qualify under the maximum or minimum Pell formulas. For 2026–27, the high-SAI restriction adds another limitation that families should understand when estimating potential awards.
Submitting the FAFSA Changes remains the most reliable way to determine eligibility. Families should not assume that participation in Medicaid, SNAP, or another public-benefit program by itself guarantees a particular Pell Grant amount without applying the current federal eligibility rules.
- Maximum Pell eligibility can depend on AGI, family size, and federal poverty guidelines.
- The maximum scheduled Pell Grant for 2026–27 is $7,395.
- An SAI of $14,790 or more generally prevents Pell eligibility, subject to specific exceptions.
Changes to Asset Reporting and Considerations
Asset reporting is one area where genuine FAFSA Changes apply specifically to the 2026–27 cycle. Recent legislation restored exclusions for certain family-owned businesses, family farms, and commercial fishing businesses when calculating the Student Aid Index.
Applicants should report only assets requested by the FAFSA and should use current net values when required. Primary residences and qualified retirement accounts remain among the categories excluded from FAFSA asset reporting under federal rules.
Because incorrect asset reporting can affect need analysis, families should use the instructions accompanying the current 2026–27 form rather than relying on guidance written for 2024–25 or 2025–26, when some business and farm rules differed.
Exclusions and Inclusions in Asset Calculations
Beginning with 2026–27, the net worth of a family-owned business with 100 or fewer full-time or full-time-equivalent employees is excluded. A family farm on which the family resides is also excluded under the current rules.
Commercial fishing businesses and related expenses owned and controlled by the family are another excluded category. Larger family businesses and farms where the family does not reside can still need to be reported according to the FAFSA instructions.
Cash, checking and savings balances and reportable investments generally remain relevant assets. Qualified retirement accounts such as 401(k)s and noneducation IRAs are excluded, while education savings accounts such as certain 529 plans are handled under specific FAFSA ownership rules.
- Family-owned businesses with 100 or fewer qualifying employees are excluded for 2026–27.
- Farms where the family resides are excluded.
- Qualified retirement-plan balances are not reported as FAFSA assets.
Parental Role and Information Requirements
Parents of dependent students can continue to play an important role as FAFSA Changes contributors. A contributor is someone required to provide information, consent and approval for federal tax-information transfer, and a signature on the FAFSA form.
Being a contributor does not make a parent legally responsible for paying the student’s college costs. The contributor designation determines whose information is necessary for the application, not who must ultimately pay tuition or accept a student loan.
Each required contributor generally needs an individual StudentAid.gov account for the online FAFSA process. Families should identify contributors early because missing required sections, consent, approval, or signatures can prevent completion of the application.
Tax Data Retrieval and Consent
Students and required contributors must provide consent and approval for federal tax information to be transferred directly from the IRS into the FAFSA. The requirement applies even when a contributor did not file a federal tax return.
If required consent and approval are not provided, the student is not eligible for federal student aid through that FAFSA application. This makes the tax-data authorization more than a convenience feature; it is a required component of the current process.
The direct transfer system replaced the older IRS Data Retrieval Tool approach. Applicants should still have appropriate tax and financial records available because some questions on the FAFSA require information that is not automatically populated through the IRS transfer.
- Required contributors must provide consent and approval for federal tax-data transfer.
- Consent is required even when no federal income-tax return was filed.
- Missing required consent prevents federal student-aid eligibility through the FAFSA.
Implications for Divorced or Separated Parents
The rule for divorced or separated parents who do not live together is based primarily on financial support rather than where the student lived most often. This differs from the residency-focused approach used under older FAFSA rules.
For 2026–27, the required parent contributor is generally the parent who provided more than 50% of the student’s financial support during the previous 12 months, even when the student lived primarily with the other parent.
If that parent is currently married, the spouse may also need to provide information. Families should use the current FAFSA instructions or the official “Who’s My FAFSA Parent?” tool when family circumstances make the contributor determination unclear.
Defining the Parent Who Provides the Most Financial Support
Financial support can include money and other assistance provided for the student’s needs. Child support or alimony paid by one parent to the other can also count toward the payer’s support when determining which parent provided more than half.
If neither parent provided more than 50% of the student’s financial support during the prior 12 months, the FAFSA generally uses the parent with the greater income and assets as the required contributor.
Families should not rely solely on custody arrangements or the student’s residential address when making this determination. The current FAFSA rule specifically focuses first on financial support when divorced or separated legal parents do not live together.
- Use the parent who provided more than 50% of financial support during the prior 12 months.
- If neither parent provided more than 50%, use the parent with greater income and assets.
- The student’s primary residence does not automatically determine the required parent contributor.
What Parents Can Do to Prepare Now
Because the FAFSA Changes for 2026–2027 are already in effect, families should move beyond general preparation and confirm whether the student’s FAFSA has been submitted, processed, and reviewed for errors or missing information.
Parents should also compare the deadlines of every school under consideration and the student’s state of legal residence. The June 30, 2027 federal deadline should not be treated as the preferred filing date because institutional and state aid can operate on earlier schedules.
After processing, review the FAFSA Submission Summary and respond promptly to requests from schools. A FAFSA submission does not itself guarantee an aid package, and colleges may request verification or additional documentation before finalizing financial aid.
Actionable Steps for Families
Confirm that the student and every required contributor have active StudentAid.gov accounts and that the correct 2026–27 form has been completed. Check contributor invitations carefully because identity or account mismatches can delay completion.
Keep tax records, current asset information, child-support records when applicable, and a list of prospective schools available. Although federal tax data are generally transferred from the IRS, additional financial questions still require accurate information from the applicant or contributor.
Finally, review the FAFSA Submission Summary after processing and contact the financial-aid office if income or family circumstances have changed substantially since the tax year used on the FAFSA. Schools can evaluate qualifying special circumstances through professional judgment.
- Complete or review the 2026–27 FAFSA as soon as possible.
- Check state and college deadlines rather than relying only on the federal deadline.
- Review the FAFSA Submission Summary and resolve errors or school requests promptly.
Resources and Support for Navigating FAFSA Changes
Official Federal Student Aid resources should be the primary reference when families need current FAFSA instructions. StudentAid.gov provides application guidance, account information, deadline explanations, Pell Grant information, and tools for identifying required parent contributors.
College financial-aid offices are especially useful when a family’s current circumstances differ significantly from the financial information reported on the FAFSA. Schools can explain documentation requirements and determine whether a professional-judgment review may be appropriate.
High-school counselors and reputable nonprofit college-access organizations can also provide application assistance. Families should be cautious about services that charge unnecessary fees simply to complete the FAFSA, because the federal application itself is free
Where to Find Reliable Information and Assistance
StudentAid.gov is the official federal resource for completing the FAFSA and reviewing current guidance. Families can also access FAFSA help materials and contact Federal Student Aid when technical or procedural questions cannot be resolved through the online instructions.
College financial-aid offices should be contacted for institution-specific deadlines, aid offers, verification requests, and special circumstances. A federal FAFSA calculation does not determine every scholarship, state grant, or institutional award available to a student.
Families reviewing the latest FAFSA Changes should prioritize official information over older articles, videos, or social-media posts. Asset definitions, Pell rules, deadlines, and form procedures can change between award years even when the overall FAFSA structure appears similar.
- StudentAid.gov is the primary official source for FAFSA guidance.
- College financial-aid offices can address institution-specific questions and special circumstances.
- State agencies should be checked for state grants, scholarships, and separate deadlines.
| Key Change | Brief Description |
|---|---|
| EFC Replaced by SAI | The Student Aid Index remains the federal need-analysis index and does not directly use the number of family members in college. |
| Simpler FAFSA Form | The streamlined FAFSA structure continues, with separate sections for students and required contributors. |
| Pell Grant Rules | The 2026–27 maximum is $7,395, with eligibility determined through federal Pell formulas and additional SAI restrictions. |
| IRS Data Exchange | Required contributors must provide consent and approval for federal tax information to transfer directly from the IRS. |
Frequently Asked Questions About FAFSA Changes
Looking Ahead: Preparing for Future FAFSA Cycles
The FAFSA Changes affecting 2026–27 demonstrate why families should review official guidance each award year instead of assuming that the previous FAFSA’s asset, Pell, or contributor rules will remain identical.
For the current cycle, the priority should be completing applications before applicable deadlines, reviewing processed information, responding to college requests, and comparing actual financial-aid offers. Families experiencing major financial changes should also ask colleges about special-circumstance reviews.
Future FAFSA cycles may introduce additional statutory or administrative updates. Staying connected to Federal Student Aid, state agencies, and college financial-aid offices provides a more reliable approach than attempting to predict future eligibility from outdated rules or generalized estimates.


