Diversified Investment Portfolio 2026: Reduce Risk 10%
Advertisements
Building a diversified investment portfolio in 2026 means spreading capital across different asset classes, sectors, and regions to reduce dependence on any single source of return.
A balanced mix of stocks, bonds, cash, and selected additional exposures can help manage concentration risk, but diversification cannot guarantee a specific reduction in losses or volatility.
The goal is to align allocation with your financial future, time horizon, liquidity needs, and tolerance for market declines while keeping costs and taxes in mind.
What Diversification Can and Cannot Do
Diversification means spreading investments among different assets so that poor performance in one holding or category does not automatically determine the result of the entire portfolio.
A diversified investment portfolio can include several asset classes and diversification within each class, such as owning companies from different sectors rather than a handful of similar stocks.
Diversification can reduce certain forms of risk, but it cannot eliminate market losses or guarantee that an investor will earn a positive return over a particular period.
Why Asset Allocation Comes First
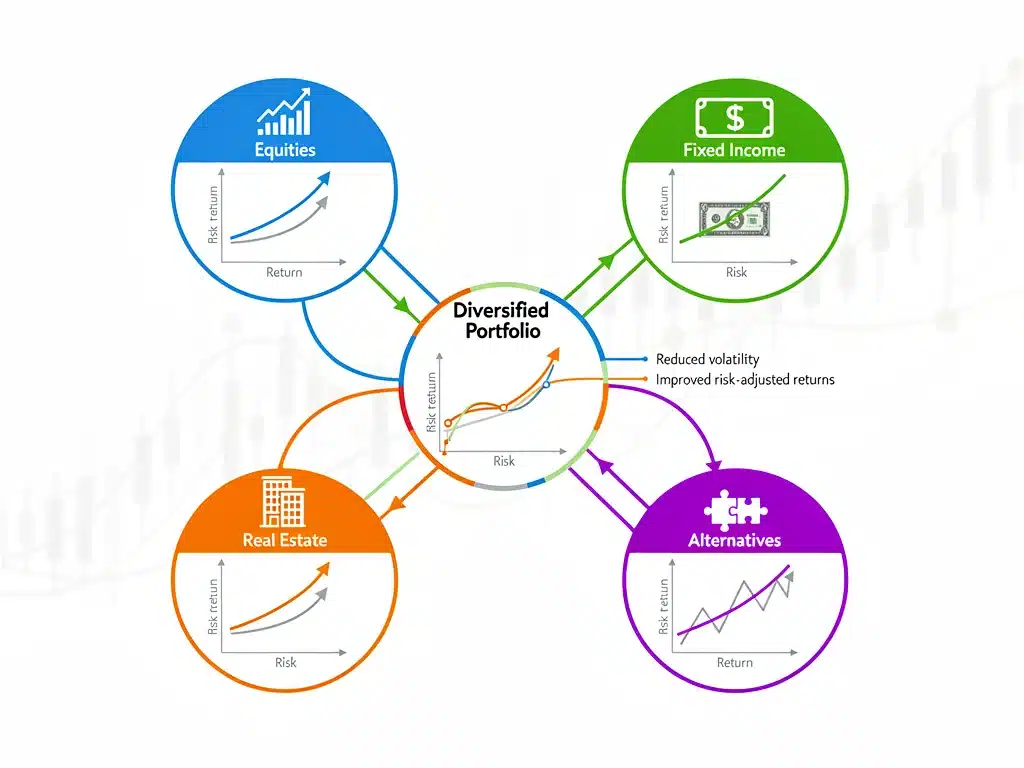
Asset allocation is the process of deciding how much of a portfolio should be invested in categories such as stocks, bonds and cash based on the investor’s objectives.
The appropriate mix depends heavily on time horizon and risk tolerance because someone investing for decades generally faces different constraints from someone who expects to use the money within a few years.
Allocation should therefore begin with personal circumstances rather than forecasts about which market segment is likely to perform best over the next twelve months.
- Define the purpose of the investment.
- Estimate when the money may be needed.
- Assess the ability and willingness to tolerate losses.
- Choose an asset mix consistent with those constraints.
Diversify Within Each Asset Class
Owning several asset classes does not automatically produce adequate diversification if each category remains concentrated in only a few securities or industries.
Within equities, diversification can include different companies, sectors, company sizes and countries, while fixed-income exposure can vary by issuer, maturity and credit quality.
Mutual funds and exchange-traded funds can make broad diversification easier, although investors should still inspect holdings because multiple funds can contain many of the same securities.
Stocks Can Provide Growth but Also Volatility
Equities provide ownership in companies and can contribute long-term growth to a portfolio, but stock prices can experience substantial declines during economic, financial or company-specific stress.
A diversified equity allocation can spread exposure across industries and businesses rather than relying heavily on a small group of companies that recently performed well.
Investors should evaluate how much stock exposure fits their horizon and tolerance for market losses instead of assuming that a particular percentage is appropriate for everyone.
Avoid Building the Portfolio Around Popular Themes
Artificial intelligence, healthcare, energy and other themes can attract significant investor attention, but popularity does not guarantee future investment portfolio returns.
A portfolio concentrated in one high-growth narrative can become vulnerable if valuations decline, expected earnings fail to materialize or technological and competitive conditions change.
Thematic investments can be included when appropriate, but they should be evaluated as specific exposures rather than treated as substitutes for broad diversification.
International Stocks Can Expand Diversification
International equity exposure can reduce exclusive dependence on U.S. companies and provide access to businesses operating under different economic and market conditions.
Foreign investments also introduce risks including currency movements, political uncertainty, regulatory differences and potentially greater volatility in some emerging markets.
The benefit therefore comes from broadening exposure rather than assuming international or emerging-market stocks will necessarily outperform U.S. equities.
Fixed Income Can Play a Different Role From Stocks
Bonds can provide income, liquidity and a different risk profile from equities, making fixed income an important part of many diversified portfolios.
However, bonds still carry risks including interest-rate risk, inflation risk, credit risk and the possibility of market losses when securities are sold before maturity.
The appropriate bond allocation depends on the portfolio’s objectives and should not be described simply as a safe portion that cannot decline in value.
Duration and Credit Quality Matter
Longer-duration bonds generally react more strongly to changes in market interest rates, while lower-quality bonds can experience larger losses when concerns about issuer creditworthiness increase.
Shorter-duration securities may be less sensitive to rate changes, but they can provide different yields and may require reinvestment sooner than longer-maturity bonds.
Investors should therefore examine maturity, duration, credit quality and expenses instead of evaluating a bond investment portfolio by yield alone.
Inflation Remains Relevant in 2026
Inflation continues to influence both household purchasing power and the real value of investment portfolio returns, making it relevant when evaluating cash and fixed-income holdings.
The Federal Reserve’s June 2026 projections showed a median PCE inflation forecast of 3.6% for 2026, while policymakers projected a median federal funds rate of 3.8% at year-end.
Those projections are not guarantees, but they demonstrate why investors should consider inflation and interest-rate sensitivity without attempting to redesign a portfolio around every economic release.
Cash Can Provide Liquidity and Stability
Cash and cash-equivalent investments generally experience less price volatility than stocks or long-duration bonds and can serve near-term spending or emergency needs.
Holding sufficient liquidity may prevent an investor from having to sell volatile assets during a market decline simply to meet an unexpected expense.
Too much cash can also create purchasing-power risk over long periods if returns fail to keep pace with inflation, making its appropriate weight dependent on the purpose of the portfolio.
Separate Emergency Savings From Long-Term Investing
Money that may be needed for emergencies or near-term obligations generally has a different objective from funds being invested for retirement many years into the future.
Keeping those goals separate can reduce the temptation to invest short-term reserves in volatile assets solely in pursuit of additional return.
It also allows the long-term portfolio to be structured around its actual investment portfolio horizon rather than being disrupted by routine household expenses.
Real Estate Can Add Another Source of Exposure
Real estate can be accessed directly through property ownership or indirectly through publicly traded real estate investment portfolio vehicles.
Property-related investments can respond differently from traditional stocks and bonds, but they remain sensitive to financing costs, economic conditions, rents and local supply and demand.
Real estate should therefore be considered based on its role in the overall portfolio rather than assuming that property automatically reduces volatility.
Publicly Traded Real Estate Is Still Market-Sensitive
Listed real estate investment portfolio trusts can provide diversified access to property sectors without requiring investors to purchase and manage individual buildings.
Because these securities trade in public markets, their prices can still move sharply during periods of changing interest rates, economic stress or shifting investor sentiment.
Investors should consider sector concentration, debt levels, expenses and underlying property exposure before using a real estate fund as a diversification tool.
Alternative Investments Require Additional Due Diligence
Commodities, private investments and other alternative assets are sometimes promoted as portfolio diversifiers because their return patterns may differ from traditional securities.
Those differences do not guarantee lower portfolio risk, and alternatives can introduce illiquidity, leverage, complex valuation methods, higher fees or limited disclosure.
Investors should understand the structure and risks of an alternative investment portfolio before adding it simply because it carries a different asset-class label.
Private Equity Is Not Appropriate for Every Investor
Private equity can provide exposure to companies outside public stock markets, but investments may require long holding periods and can be difficult to value or sell.
Fees and minimum investment portfolio requirements may also be materially different from those associated with ordinary public-market funds.
Its suitability therefore depends on liquidity needs, investment knowledge and access rather than an assumption that private assets automatically improve diversification.
Crypto Assets Should Not Be Treated as Automatic Diversifiers
Blockchain technology and crypto assets are frequently discussed together, but investing in a crypto asset is not the same as investing in the underlying technology or companies developing blockchain systems.
Crypto prices can be highly volatile, and investors may also face custody, liquidity, operational and regulatory risks depending on how exposure is obtained.
Any crypto allocation should therefore be evaluated as a potentially speculative investment rather than presented as a guaranteed source of diversification or protection.
Understand Custody and Product Structure
Directly holding crypto assets involves questions about wallets, private keys and custody arrangements that do not arise in the same way with conventional brokerage securities.
Exchange-traded products can provide another form of exposure to assets such as bitcoin or ether, but the underlying investments remain highly speculative and can experience large price movements.
Investors should understand exactly what they own, how the product tracks the underlying asset and which investor protections apply before allocating capital.
ESG Investing Does Not Guarantee Lower Risk
ESG investing incorporates environmental, social or governance considerations into investment portfolio selection, but funds can define and apply those factors in very different ways.
A fund labeled as ESG can perform either better or worse than the broader market, and the label itself does not establish superior management, resilience or expected returns.
Investors should therefore evaluate ESG strategies according to their objectives, holdings, methodology, fees and fit within the overall portfolio rather than treating the designation as a risk-reduction guarantee.
ESG Ratings Can Differ Significantly
Different rating providers can evaluate the same company using different criteria, data sources and weighting systems, producing materially different conclusions.
An investor interested in sustainability should review the fund’s prospectus, holdings and stated methodology instead of relying solely on a third-party score or marketing label.
This review also helps determine whether the strategy genuinely reflects the investor’s preferences or merely adds another overlapping portfolio exposure.
Rebalancing Helps Control Portfolio Drift
Over time, stronger-performing assets can grow into a larger percentage of a portfolio than originally intended, increasing exposure to risks the investor did not deliberately choose.
Rebalancing means bringing the allocation back toward its target mix by selling overweight positions, directing new contributions toward underweight assets or using a combination of both approaches.
The purpose is to maintain the chosen risk profile rather than predict which investment portfolio will perform best next.
Use a Consistent Rebalancing Rule
Some investors review allocations on a calendar schedule, while others consider rebalancing only when an asset class moves beyond a predetermined tolerance range.
Investor.gov notes that approaches can include periodic reviews such as every six or twelve months or threshold-based methods triggered by meaningful allocation changes.
The appropriate schedule should also consider taxes and transaction costs because excessive trading can create unnecessary expenses without improving diversification.
Dynamic Market Timing Is Not Required for Diversification
A diversified portfolio does not need to be repeatedly repositioned according to short-term economic forecasts or predictions about the next market winner.
Changing allocation frequently in response to headlines can turn a long-term risk-management plan into a market-timing strategy with uncertain results.
Adjustments are generally more defensible when the investor’s goals, horizon, liquidity needs or tolerance for losses change materially.
Economic Forecasts Are Useful but Uncertain
Federal Reserve projections, inflation data, employment reports and economic forecasts can provide context for understanding the environment in which investments operate.
They should not be interpreted as precise instructions for moving an entire portfolio because economic outcomes regularly differ from projections.
A resilient allocation should therefore be capable of operating across several plausible scenarios instead of depending on one forecast being exactly correct.
Geopolitical Risk Supports the Case for Broad Exposure
Trade disputes, military conflicts, sanctions and political changes can affect currencies, commodities, industries and individual national markets.
Holding investments across different countries and sectors can reduce exclusive dependence on one economy, although global shocks can still cause many markets to decline together.
International diversification should therefore be viewed as a way to reduce concentration rather than as complete protection from geopolitical volatility.
Defensive Sectors Are Not Guaranteed Safe Havens
Consumer staples, utilities and healthcare companies are sometimes described as defensive because demand for many of their products can remain relatively stable during economic weakness.
These stocks can still decline because of valuation, regulation, interest rates, company-specific problems or broad market stress.
Sector diversification is more reliable than assuming that one defensive category will always protect the portfolio during the next downturn.
Define Goals Before Choosing Investments
Portfolio construction should begin with the financial objective the money is intended to support rather than with a list of securities currently receiving media attention.
A retirement portfolio, home-purchase fund and short-term reserve can require very different levels of risk because the expected withdrawal dates are different.
Clear objectives make it easier to select investments and evaluate whether the portfolio remains appropriate as circumstances change.
Assess Risk Tolerance Realistically
Risk tolerance includes both the financial ability to absorb losses and the emotional willingness to remain invested during periods of substantial market decline.
A portfolio that appears optimal during rising markets may prove inappropriate if normal volatility causes the investor to sell during every downturn.
Choosing a sustainable risk level can therefore be more important than pursuing the highest theoretical return available from a more aggressive allocation.
- Define the financial goal.
- Set the expected investment portfolio horizon.
- Estimate liquidity needs.
- Consider the financial ability to withstand losses.
- Consider emotional tolerance for volatility.
Low-Cost Funds Can Simplify Diversification
Mutual funds and exchange-traded funds can provide exposure to dozens, hundreds or even thousands of securities through one investment portfolio vehicle.
Broad-market funds can simplify diversification for investors who do not want to select and monitor large numbers of individual securities themselves.
However, investors should compare expenses, underlying holdings, index methodology, liquidity and tax considerations because not every ETF or mutual fund is broadly diversified.
Check for Hidden Portfolio Overlap
Owning several funds can create the appearance of diversification while repeatedly exposing the investor to many of the same large companies or sectors.
Reviewing top holdings and sector allocations can reveal whether supposedly different funds actually provide substantially overlapping exposure.
A smaller number of broadly diversified funds may sometimes produce a clearer portfolio than a large collection of narrowly focused products.
Fees and Taxes Affect Diversification Decisions
Investment portfolio costs reduce the amount of return retained by investors, making expense ratios, commissions and advisory fees relevant when comparing portfolio structures.
Rebalancing in taxable accounts can also trigger capital gains or other tax consequences depending on the securities sold and the investor’s circumstances.
A strategy should therefore evaluate whether the benefit of a portfolio adjustment justifies its transaction and tax costs rather than rebalancing mechanically without review.
Use New Contributions Before Selling When Practical
Investors who are regularly adding money to a portfolio may sometimes restore allocation by directing new contributions toward underweight asset classes.
This approach can reduce the need to sell appreciated investments solely for rebalancing purposes, although it may not correct large allocation differences quickly enough in every situation.
The SEC identifies adjusting new contributions as one of several ways investors can bring a portfolio back toward its desired allocation.
Derivatives Are Specialized Risk-Management Tools
Options and futures can be used to hedge specific market exposures, but they also introduce complexity, leverage, expiration risk and potentially substantial losses.
Buying a put option, for example, can provide defined downside protection for a period of time, but the premium paid for that protection can expire worthless.
Derivatives should therefore not be presented as a required component of an ordinary diversified portfolio or as an easy method for achieving a target risk reduction.
Simple Diversification May Be More Appropriate for Many Investors
Broad asset allocation, diversified funds, adequate liquidity and periodic rebalancing can address many common portfolio risks without requiring complex derivative strategies.
Investors considering options, futures or leveraged products should understand the mechanics, maximum potential loss and circumstances under which the hedge may fail to behave as expected.
Professional assistance may be appropriate when a proposed strategy is difficult to understand or depends heavily on leverage and sophisticated risk calculations.
Measure Risk Before Claiming It Has Been Reduced
The original idea of reducing portfolio risk by exactly 10% is incomplete because investment portfolio risk can be measured in several different ways.
Volatility, maximum drawdown, downside deviation, concentration and probability of failing to meet a financial goal describe different dimensions of risk and can produce different conclusions.
A valid claim that risk fell by 10% would therefore require a defined metric, starting portfolio, comparison portfolio, measurement period and methodology.
Focus on Risks You Can Actually Control
Investors cannot control market returns, interest rates or geopolitical events, but they can influence diversification, concentration, fees, liquidity and the amount of risk they choose to accept.
They can also avoid unnecessary leverage, maintain an emergency reserve and select an allocation appropriate for the timeframe in which the money will be needed.
These actions do not guarantee a particular return, but they create a more disciplined framework for managing uncertainty.
Review the Portfolio Without Overreacting
A portfolio should be reviewed periodically to confirm that its allocation, costs and investments remain consistent with the original financial objective.
Reviewing does not mean changing investments every quarter, because short-term underperformance alone is not necessarily evidence that the strategy has failed.
Changes should be based on meaningful allocation drift, altered personal circumstances or evidence that an investment portfolio no longer performs the role for which it was selected.
Rebalance Back Toward the Target When Needed
If equities rise enough to become substantially larger than the target allocation, rebalancing can reduce that concentration and restore the intended mix.
If another asset class becomes underweight, new contributions or selected purchases can help move it back toward the planned percentage.
This disciplined process prevents recent market winners from silently transforming the portfolio into a riskier allocation than the investor originally selected.
- Review asset allocation periodically.
- Check for concentration and fund overlap.
- Evaluate fees and tax consequences.
- Rebalance when allocation drift becomes meaningful.
| Key Strategy | Practical Application |
|---|---|
| Asset Allocation | Divide the portfolio among asset classes according to goals, time horizon, liquidity needs and risk tolerance. |
| Diversification | Avoid excessive dependence on one company, sector, country or investment portfolio theme. |
| Cost Control | Compare fund expenses, transaction costs and potential tax consequences before changing investments. |
| Rebalancing | Restore the target allocation when portfolio drift creates more concentration or risk than originally intended. |
Frequently Asked Questions About Investment Diversification
Not as a universal rule. A specific 10% reduction could only be demonstrated after defining the portfolio, comparison benchmark, risk metric and measurement period. Diversification can reduce certain risks, but the result varies.
Common categories include stocks, bonds and cash. Depending on an investor’s circumstances, additional exposure may include real estate or other investments whose risks and costs are clearly understood.
No. A portfolio can be broadly diversified without crypto assets or private investments. These exposures introduce additional risks and should only be considered when they fit the investor’s objectives and risk tolerance.
No. ESG funds use different methodologies and can perform better or worse than conventional investments. Investors should review holdings, methodology, fees and objectives before investing.
There is no single required schedule. Some investors use periodic reviews such as every six or twelve months, while others rebalance when allocations move beyond predetermined ranges.
Looking Ahead: Building a Resilient Portfolio
Building a diversified investment portfolio in 2026 should focus on controlling concentration, costs and allocation rather than promising a predetermined percentage reduction in risk or identifying guaranteed market winners.
Stocks, bonds, cash and carefully selected additional exposures can play different roles, while periodic rebalancing helps prevent market movements from gradually changing the intended risk profile.
The most durable strategy is one built around personal goals, realistic risk tolerance and a long-term plan that can remain useful across different economic conditions instead of depending on short-term forecasts being correct.


